

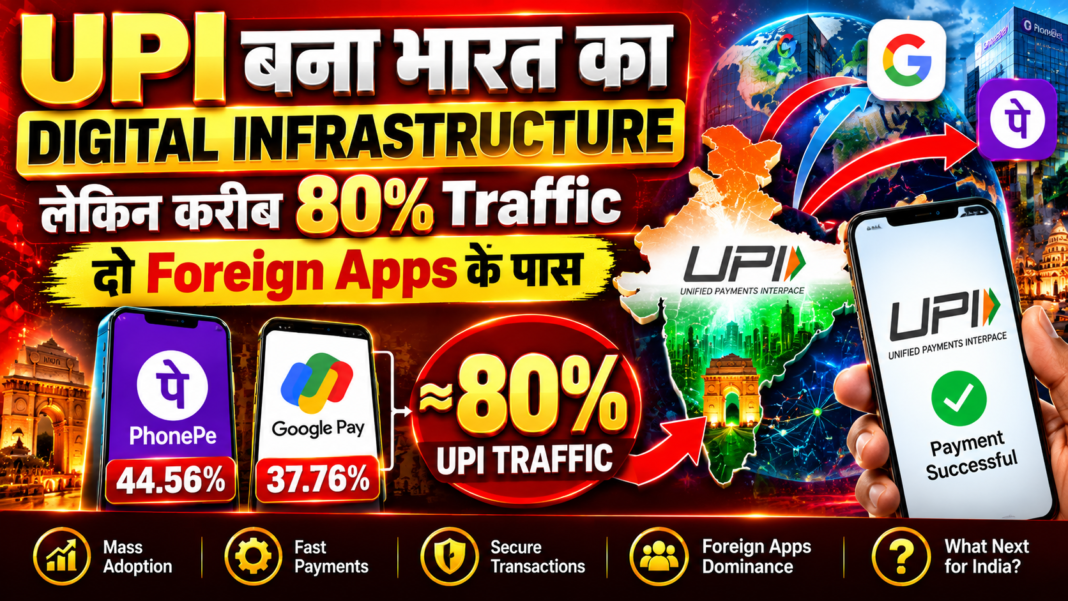

UPI Digital Infrastructure ने भारत के digital payments को बदल दिया है, लेकिन PhonePe और Google Pay मिलकर करीब 80% UPI transaction volume संभालते हैं। जानिए पूरी कहानी।UPI खुद किसी एक private app की property नहीं है। यह भारत का interoperable instant-payment infrastructure है, जिसे NPCI operate करता है। लेकिन consumers जिस app के जरिए UPI इस्तेमाल करते हैं, उस front-end layer में PhonePe और Google Pay की combined share करीब 80% के आसपास बनी हुई है, हालांकि यह महीने-दर-महीने बदलती रहती है।
भारत में digital payments की कहानी पिछले कुछ वर्षों में तेजी से बदली है। आज छोटी दुकान से लेकर बड़े showroom, online shopping, bill payment और व्यक्ति-to-व्यक्ति transfer तक UPI का इस्तेमाल किया जाता है।
इसी वजह से UPI Digital Infrastructure अब केवल payment का एक तरीका नहीं रह गया है। यह भारत की digital economy की एक महत्वपूर्ण foundation बन चुका है।
लेकिन इसी success के साथ एक बड़ा सवाल भी सामने आया है। UPI का underlying infrastructure भारतीय ecosystem द्वारा संचालित होने के बावजूद, इसके customer-facing app layer पर दो बड़े foreign-origin technology groups के apps का बहुत बड़ा हिस्सा है।
यही वजह है कि आज UPI Digital Infrastructure और उसके ऊपर बने app ecosystem की market concentration पर चर्चा तेज हो रही है।
UPI Digital Infrastructure क्या है?
UPI Digital Infrastructure को आसान भाषा में समझें तो यह ऐसा payment network है जो अलग-अलग banks और payment applications को एक common interoperable system से जोड़ता है।
UPI के जरिए user अपने bank account से दूसरे bank account में तुरंत payment कर सकता है। इसके लिए beneficiary का bank अलग हो सकता है और payment app भी अलग हो सकता है।
यही interoperability UPI को traditional wallet model से अलग बनाती है। एक user PhonePe इस्तेमाल कर सकता है और दूसरा Google Pay या किसी अन्य UPI app का उपयोग कर सकता है, फिर भी दोनों UPI network के जरिए payment कर सकते हैं।
Customer → UPI App → PSP/Bank Ecosystem → UPI Network → Receiver Bank → Receiver
UPI Digital Infrastructure कितना बड़ा हो चुका है?
NPCI के official statistics के अनुसार August 2026 में UPI पर लगभग 24,508.96 million transactions हुए और उनका total value लगभग ₹29,82,355.95 crore था। उस महीने 752 banks UPI पर live थे। :chatgpt-content-reference{index=”1″}
इस scale से अंदाजा लगाया जा सकता है कि UPI Digital Infrastructure अब केवल metropolitan cities तक सीमित technology नहीं है। इसका इस्तेमाल देशभर में consumers और merchants दोनों करते हैं।
करीब 80% UPI Traffic दो Apps के पास क्यों?
यहां “80%” को एक fixed permanent number समझना सही नहीं होगा। UPI app market share हर महीने बदलती है।
May 2026 में PhonePe और Google Pay की combined UPI transaction-volume share करीब 79% थी। :chatgpt-content-reference{index=”2″}
June 2026 के available app-share data में PhonePe की share 44.56% और Google Pay की 37.76% दिखाई गई, यानी दोनों मिलकर करीब 82.32% थे। :chatgpt-content-reference{index=”3″}
वहीं August 2026 के data में PhonePe और Google Pay की combined share करीब 78.3% बताई गई है। इसलिए headline में “करीब 80%” कहना अधिक accurate है, जबकि exact percentage month के अनुसार बदलता है।
PhonePe + Google Pay = करीब 80%
Exact share month-to-month बदल सकती है।
UPI App Market में PhonePe और Google Pay की Position
| App | June 2026 Volume Share | Position |
|---|---|---|
| PhonePe | 44.56% | Largest app |
| Google Pay | 37.76% | Second largest |
| Paytm | 6.88% | Major challenger |
| Navi | 2.55% | Growing player |
| super.money | 1.32% | Emerging player |
Note: ऊपर के percentages June 2026 के available app-share data पर आधारित हैं। Market share लगातार बदलती रहती है। :chatgpt-content-reference{index=”4″}
दो Foreign Apps का इतना बड़ा दबदबा कैसे बना?
PhonePe और Google Pay दोनों का origin और ownership structure भारत के बाहर से जुड़े बड़े technology/business groups से संबंधित है। लेकिन इसका मतलब यह नहीं है कि UPI network itself foreign-owned है।
यह distinction समझना बहुत जरूरी है। UPI Digital Infrastructure का underlying payment rail भारत के NPCI-led ecosystem का हिस्सा है, जबकि PhonePe और Google Pay जैसे apps उस infrastructure के ऊपर customer-facing interface provide करते हैं।
इन apps की popularity के पीछे कई factors हैं—large user bases, merchant acceptance, familiar user interface, cashback/rewards history, strong brand presence और existing technology ecosystems।
UPI Digital Infrastructure में Concentration चिंता का विषय क्यों?
जब किसी digital payment ecosystem में बहुत बड़ा transaction volume कुछ ही apps के जरिए जाता है, तो operational concentration का सवाल उठता है।
अगर किसी बड़े app में technical outage, security incident या service disruption होता है तो बहुत बड़ी संख्या में users प्रभावित हो सकते हैं।
इसीलिए UPI Digital Infrastructure में multiple strong competitors का होना ecosystem resilience के लिए महत्वपूर्ण माना जाता है।
- Operational dependency
- Competition pressure
- Innovation और feature access
- Consumer choice
- System resilience
UPI Market Share Cap का क्या हुआ?
NPCI ने पहले third-party UPI apps की market concentration को सीमित करने के लिए 30% market-share cap का framework बनाया था। इसका उद्देश्य ecosystem में competition और diversification को बढ़ावा देना था।
हालांकि implementation timeline कई बार बदली है। 2026 में भी यह मुद्दा महत्वपूर्ण बना हुआ है और existing large players तथा smaller apps के बीच market-share balance पर चर्चा जारी है।
Business Standard के अनुसार third-party UPI app market-cap implementation की deadline December 31, 2026 तक बताई गई है। :chatgpt-content-reference{index=”5″}
क्या Indian UPI Apps का Share बढ़ सकता है?
हाँ। UPI ecosystem में Paytm, BHIM, Navi, super.money और कई अन्य apps मौजूद हैं। इन platforms का market share अभी leading two apps से काफी कम है, लेकिन competition बढ़ाने में इनकी भूमिका महत्वपूर्ण हो सकती है।
BHIM government-backed UPI app है और 2026 में इसके transaction volumes में तेजी देखी गई। Business Standard के अनुसार January 2026 में BHIM ने लगभग 172 million UPI transactions process किए थे। :chatgpt-content-reference{index=”6″}
इसके अलावा smaller fintech apps cashback, credit products, rewards और specialized features के जरिए users को attract करने की कोशिश कर रहे हैं।
UPI Digital Infrastructure और Digital India का भविष्य
भारत ने जिस scale पर UPI को अपनाया है, वह global digital payments landscape में भी महत्वपूर्ण development है। Government data के अनुसार FY2025-26 में UPI ने लगभग 24,161.69 crore annual transactions process किए और भारत के digital payments volume में इसका share करीब 85% था। :chatgpt-content-reference{index=”7″}
इसलिए UPI Digital Infrastructure का future केवल payment apps की competition तक सीमित नहीं है। इसके साथ credit, insurance, investment, merchant services, international payments और digital commerce जैसी कई categories जुड़ रही हैं।
आने वाले समय में competition का असली फायदा consumers को बेहतर user experience, faster innovation, improved security और ज्यादा choices के रूप में मिल सकता है।
2026 में UPI के सामने नई चुनौतियां
UPI का scale बढ़ने के साथ इसके financial sustainability model पर भी चर्चा हो रही है। सितंबर 2026 की reports के अनुसार 15 October 2026 से ₹2,000 से अधिक eligible merchant UPI transactions पर नया MDR framework लागू होने वाला है, जबकि person-to-person payments पर यह charge लागू नहीं है। :chatgpt-content-reference{index=”8″}
इस तरह UPI Digital Infrastructure के सामने आने वाले वर्षों में केवल transaction growth ही मुद्दा नहीं होगा। Sustainability, merchant economics, competition और consumer convenience भी उतने ही महत्वपूर्ण होंगे।
UPI और Digital Credit से जुड़ी हमारी दूसरी Guides
अगर आप UPI, Credit Line और digital payment products के बारे में और जानकारी चाहते हैं, तो NK Digital Point की ये related guides भी पढ़ सकते हैं।
UPI Credit Guide: BharatPe Flex Credit Line on UPI 2026
Bank Credit Guide: HDFC Credit Line on UPI 2026
Pay Later Guide: Super Money Pay in 6 और Pay Later 2026
Official UPI Sources
NPCI Official: UPI Product Statistics
Government of India: Press Information Bureau
UPI Digital Infrastructure आम Users के लिए क्यों जरूरी है?
एक आम consumer के लिए UPI सिर्फ QR code scan करके payment करने का तरीका दिखाई देता है। लेकिन इसके पीछे banks, payment service providers, NPCI, technology companies और merchant systems का बड़ा network काम करता है।
यही पूरा ecosystem UPI Digital Infrastructure को मजबूत बनाता है। User किसी भी participating app से payment कर सके और receiver किसी दूसरे bank/app ecosystem में payment receive कर सके—यह interoperability UPI की सबसे बड़ी ताकतों में से एक है।
UPI Digital Infrastructure — Final Verdict
भारत का UPI ecosystem आज दुनिया के सबसे बड़े real-time payment systems में से एक बन चुका है। इसकी success का सबसे बड़ा कारण interoperability, bank connectivity और आसान mobile payment experience है।
लेकिन app layer पर PhonePe और Google Pay का combined share करीब 80% के आसपास होना competition और concentration को लेकर सवाल जरूर खड़ा करता है। Exact percentage महीने के अनुसार बदलती है, इसलिए इसे fixed 80% नहीं समझना चाहिए।
UPI Digital Infrastructure का future तभी और मजबूत होगा जब underlying payment network के साथ-साथ customer-facing app ecosystem में भी healthy competition, innovation और multiple strong alternatives मौजूद रहें।
UPI Digital Infrastructure — FAQs
UPI क्या भारत का Digital Infrastructure है?
UPI भारत के digital payment ecosystem का एक महत्वपूर्ण infrastructure layer है, जो banks और payment applications को interoperable instant-payment system से जोड़ता है।
क्या PhonePe और Google Pay मिलकर 80% UPI traffic रखते हैं?
Combined share करीब 80% के आसपास रही है, लेकिन exact percentage हर महीने बदलती है। May 2026 में करीब 79% और August 2026 में करीब 78.3% reported/derived volume share थी।
क्या UPI foreign companies का network है?
नहीं। UPI का underlying payment infrastructure NPCI-led Indian payments ecosystem का हिस्सा है। PhonePe और Google Pay customer-facing payment applications हैं जो UPI ecosystem पर operate करते हैं।
UPI को कौन operate करता है?
UPI का संचालन National Payments Corporation of India यानी NPCI करता है।
UPI के दूसरे बड़े apps कौन से हैं?
PhonePe और Google Pay के अलावा Paytm, BHIM, Navi, super.money, CRED, Amazon Pay और अन्य UPI applications भी ecosystem में मौजूद हैं।
इस वेबसाइट पर प्रकाशित सभी सरकारी योजनाओं, लोन योजनाओं और सब्सिडी से जुड़ी जानकारी विभिन्न समाचार स्रोतों, आधिकारिक दस्तावेजों और सार्वजनिक डोमेन में उपलब्ध डाटा के आधार पर संकलित की जाती है।
हम किसी भी योजना का संचालन नहीं करते हैं और न ही किसी प्रकार की वित्तीय सहायता प्रदान करते हैं। योजनाओं की पात्रता, नियम और शर्तें समय-समय पर बदल सकती हैं।
किसी भी योजना का लाभ उठाने से पहले कृपया संबंधित सरकारी विभाग, बैंक या आधिकारिक पोर्टल पर विवरण की पुष्टि अवश्य करें। इस वेबसाइट का उद्देश्य केवल जानकारी उपलब्ध कराना है।